Over the next few Professional Advisor emails, we’ll be sharing a few of the conversations and ideas we covered at our Professional Advisor Rooftop Sunset Social(opens in new tab) in August.
This month, we’re starting with Qualified Charitable Distributions (QCDs), a topic Terri Munro discussed at the event.
And because sometimes the best way to understand an idea is to see it in action, we’re also sharing the story of Bill and Ginger Dallas and how they’re using a QCD to make the most of their charitable giving.
We hope you find both helpful, and can share it with your clients when the time is right.
A Tax-Smart Way to Support the Causes You Care About
WHAT IS A QCD?
- A Qualified Charitable Distribution (QCD) is a direct transfer from an IRA to a qualified charitable organization for IRA owners over 70.5 of age
- The distribution is excluded from taxable income
- Funds must be sent directly from the IRA trustee to the charity
- Donor-advised funds and private foundations are not eligible recipients
WHO CAN BENEFIT?
- IRA owners age 70½ or older may make a QCD
- Individuals who are charitably inclined and looking for tax-efficient giving strategies
- Those who must take Required Minimum Distributions (RMDs) but do not need the income
HOW QCDs WORK WITH RMDs
- QCDs count toward satisfying your annual Required Minimum Distribution
- RMDs generally begin at age 73 (and for some individuals may begin as late as age 75, depending on birth year)
- While a QCD can exceed your RMD amount, any excess does not carry forward to future years’ RMD requirements
2026 CONTRIBUTION LIMITS
- Up to $111,000 per individual/ $222,000 for married couples over 70.5
POTENTIAL TAX ADVANTAGES
- May help keep you in a lower tax bracket
- Can reduce taxes on Social Security benefits
- May help lower Medicare premiums that are affected by income levels
- May help avoid phaseouts of other tax deductions and credits
- Avoids new charitable deduction limitations, including:
- The 0.5% floor on charitable deductions
- Overall itemized deduction limitations
WHEN A QCD MAY MAKE SENSE
- You are required to take an IRA distribution but do not need the funds for living expenses
- Including your RMD in income would increase your tax liability
- You want to reduce future RMDs by lowering your IRA balance
KEY TAKEAWAYS
- A QCD helps eligible IRA owners give to charity, satisfy RMDs and potentially reduce taxable income
Community Foundation Opportunties
QCDs cannot be made to donor-advised funds or private foundations. However, they can fund:
- Designated Funds: support a specific nonprofit
- Field of Interest Funds: support a cause such as education, health care, or the arts
- Unrestricted Funds: support changing community needs
Sometimes generosity isn’t about giving more. It’s about making the most of what you give.
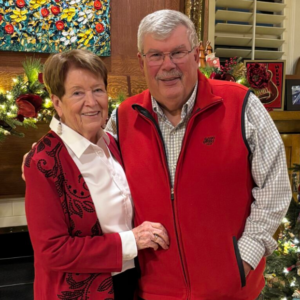
Bill and Ginger Dallas have been giving through their donor advised fund at Cobb Community Foundation for more than ten years. Along the way, they’ve supported their church, helped build Gracepoint School, created scholarships at Kennesaw State University and Marietta Country Club, contributed to Match Magic nonprofits, helped fund the campaign’s match pool, and so much more. Giving is simply part of how they show up for their community.
“We focus our giving on people more than causes,” Bill said. “We care about charities that support families and individuals, scholarships, helping people break free from addiction, and programs like Circles that help people improve their lives by connecting them with role models and opportunities.”
Then, they discovered a way to make their giving go even further. In 2025, Bill turned 73 and was required to begin taking distributions from his IRA.
“I didn’t want a tax bill just for moving money,” Bill says.
Because CCF had already talked with Bill and Ginger about Qualified Charitable Distributions, he knew there was a better option. In 2026, Bill is using his entire required distribution to support the causes he cares about — without increasing his taxable income. One check from his IRA flows through his new CCF Pass-Through Designated Fund to support scholarships, fulfill charitable commitments, maintain the Dallases’ Catalyst Society membership, and help fund the 2026 Match Magic match pool.
“My advisor cuts one check, and CCF handles the rest,” Bill says. “They made it easy. We’ll do this every year.”
BEST-KEPT GIVING SECRET: IRA QUALIFIED CHARITABLE DISTRIBUTIONS
Qualified Charitable Distribution (QCD) is a smart option for people who are already giving to charity, don’t need extra income, and are required to take IRA distributions. Instead of taking your required minimum distribution (RMD), paying income tax on it, and then donating what’s left, a QCD sends the money directly from your IRA to charity. That amount never shows up as taxable income, which can mean lower overall taxes, reduced Medicare premiums, and less tax on Social Security. In short, you give the same amount to charity—but keep more for yourself by avoiding avoidable taxes. Professional Advisors, if you have clients like Bill and Ginger Dallas—philanthropic, over the age of 73, and looking to make an impact in the community—Cobb Community Foundation would love to talk through possibilities with you. And as always, we’re grateful for the opportunity to support you and your clients. We’re here to be a resource and a collaborative partner.